National Life Recognized As One Of ‘America’s Magnificent Eight’ | National Life

National Life Recognized As One of ‘America’s Magnificent Eight’

CEO Forum

Montpelier, VT –  (March 28, 2018)  National Life Group has been recognized as one of “America’s Magnificent Eight Exceptional Companies” by CEO Forum, a media company that highlights the innovative work of chief executives from around the country.

Additionally, Mehran Assadi, National Life’s chairman, CEO and president, was featured in a column on Forbes.com in which seven CEOs shared their insights into building an exceptional business.

Robert Reiss, the CEO of CEO Forum, said four criteria were used in determining who to include on the “Magnificent Eight” list. He included companies that had an incredible and aligned culture; provided exceptional customer experience; have strong financials; and have a higher purpose.

“Through all my research, there are few companies who have all of these elements to the degree National Life does,” Reiss said. “After my first time visiting National Life Group in 2016 and again this year I was frankly blown away by the remarkable caring and focused culture. And not just one person. Every person I met had that same passion, and actually contributes to their own cause.”

National Life’s Assadi was one of about 750 CEOs that Reiss interviewed and considered for inclusion among the “Magnificent Eight.”

Assadi said the key to building and sustaining an exceptional business is “a clear strategy, a strong culture, a purpose-driven and performance-oriented team—resulting in exceptional execution.  It all ties together: First, you dream it. If your dreams do not scare the heck out of you, then they are not big enough. Tie your dreams to a worthy cause and connect your team to the cause. Create a movement.”

For the past 10 years National Life has recorded record growth in sales and earnings and is one of the fastest growing life insurance companies in the country. Chartered in 1848, it holds true to its values to Do good. Be good. Make good.

CEO Forum is rolling out the “Magnificent Eight” in a series of audio interviews and in its magazine over the next several weeks. The print edition of the magazine is being mailed this week.

At National Life Group, our cause is to create positive change in people’s everyday lives. From our products and services to all the good we do in our communities, we dedicate ourselves to ensuring a better future – one person at a time. Learn more at NationalLife.com.


Source: National Life Recognized As One Of ‘America’s Magnificent Eight’ | National Life

Medicare’s Trust Fund Is Set to Run Out in 8 Years. Social Security, 16. – The New York Times

Today’s rant… The demise of Medicare and Social Security. Oh my lord!!!

Source: Medicare’s Trust Fund Is Set to Run Out in 8 Years. Social Security, 16. – The New York Times

Click the link above for the article. This is not good news sadly. For years they have been estimating when Social Security and Medicare would run out of money. It seems like every time they update the estimate, the end date is moved a smidge closer to now… and it happened again.

Now they are saying Social Security will run out in sixteen years or 2034 and Medicare will run out in just another eight years or 2026.

Medicare is a real problem, just when you think about the timing. So they are telling us it will be done, right when the biggest group of baby boomers are probably going to need healthcare services. Right?

Wow. that is just nuts. So, we are going to be a bunch of old farts and no one to take care of us. Which we already knew any ways, being that the average age of a nurse is above 53. They cannot keep working forever. So what do you think when in 20 years, the average age of a nurse will be 60 or more… but the number of patients will be double? Right? Boomers Rule!!!!

However, we will not have money for our healthcare or our groceries by then. Social security will be gone.. healthcare will be in shambles.

And, all this has been known for, well…. like, forever. Politicians did not want to deal with the problem because the solutions are politically unfavorable. Meaning, if they wanted to work on a solution, no matter the solution, they are going to have to piss someone off. Pissed off constituents translate into votes for candidates who don’t do anything, being that no action is better than a wrong action in their minds. So, by trying to do right, a decent politician will end up possibly out of work. They know this. So, they have not done anything.

It’s all just a mess. This is what our government has left us with.

No healthcare soon. No income either.

Good job government.

Rant over.


Attend an online class on a Saturday morning.

Bring coffee and donuts. Robes are optional.

  • The class lasts only 30 minutes. (Q/A time is extra)
  • It’s FREE! No cost. No obligation.
  • All you need is a computer, internet, and sound to hear me. A mic if you want me to hear you.
  • No one can hear you if you do not chose. No one can see you either. No personal information will be discussed.
  • I cover it all in this short presentation. From here, you will know if you want to meet face-2-face to discuss this strategy for your own life.

FREE!!! The 7 Steps Presentation!

During this fast-paced, fun presentation we will discuss the following 7 topics.

  • STEP 1 – Knowledge – A discussion about the game of Life!
  • STEP 2 – Cash Flow – How banks leverage cash flow and how you
    can leverage your own cash flow just like they do!
  • STEP 3 – Debt – How to keep more of your money from going away from you!
  • STEP 4 – Taxes – How to NOT pay them legally!
  • STEP 5 – Risk – What risks are you facing.
  • STEP 6 – “The Big Picture” – The benefits of the “Big Picture” plan!
  • STEP 7 – Your Decision – How to Proceed and get your own FREE “Big Picture Plan” report that will show you how you can pay off all your debt in 9 years or less, including your mortgage and student loans, guaranteed, without spending anything more than you are right now!

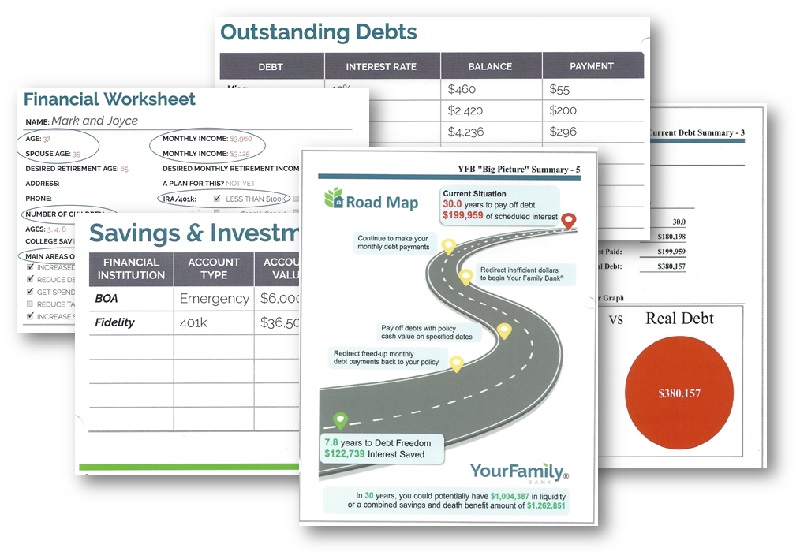
In this presentation, we will share with you the story of the actual case of “Mark & Joyce”; a young couple YFB saved more than $122,000 in interest expense. This is not outrageous. This is just typical. YFB has done that for 1,000’s of clients across the USA.

You will learn all about our FREE “Big Picture” Report offer. Trust me… you want this report! In this report, you will be able to clearly get all the facts; all the guarantees, all the numbers.

A Big Picture Report will show you;

  • EXACTLY how fast you can pay off all your debt through YFB.
  • EXACTLY how much interest it will save you.
  • EXACTLY how much you will lose out on over the course of your life if you do NOT do it. It’s staggering.

Simple. It’s all guaranteed.

That’s it. That’s the story. Now, get registered for an upcoming class. What are yah waiting for? This is your invitation!

REGISTER FOR AN UPCOMING CLASS

Pick the First Date that Has a Vacant Seat.

Go to Calendar of Events


Facebook Comments Added

We have added a Facebook comments section. You need not register for our site… just simply leave a comment using your Facebook account. I just thought this might be easier and I would like to hear feedback on my writings.

Thanks always.

Michael Todd Oldfield


Part 2 – My Focus These Days… And Why

In part 1 of this little literary gem I shared my background and where I have been over the last thirty seven years. If you have not read it, please, really… the first 400 pages really moves fast. Hahahahaha. I crack myself up.

Let’s talk about the present now and on what I my focus my professional career; and how that I might be able to help you you. I guess if you really wanted to boil down my work; I do two things really well.

  1. I help people save as much money as possible. Whether that is by cutting healthcare expenses,

I am an independent, licensed and appointed, health and life insurance broker.

What does this mean? I know it’s a mouthful. Let’s break it apart. First, it means I am independent. I am not captive to one particular company, presenting their products. I can remain objective. I represent many, many companies. This is the great thing about being an independent broker. I can remain on YOUR side and not one particular company’s side. It also means that I have no boss. I have no one putting “sales quotas” on my back; no one pressuring me to sell, sell, sell. I hate that crap. I am not much of a sales person I presume.

I just hate feeling like I have any kind of agenda that is not directly tied to what someone has told me they need, or that solves a problem I know they have. Even though some times people do not know when they have a problem, and it is staring them right in the face.

So, I spend a lot of time reading, learning, and educating myself. I am always looking for ideas that will benefit the 100’s of clients I serve. Sometimes, I will find small solutions. Sometimes I find something HUGE! I love those days.  LOL

Second, I am a licensed and appointed. I am licensed by the state of Kentucky’s Department of Insurance (Lic#814418) to be a health and life agent. This means I am continually being tested and I maintain professional insurance, bonding, and educational requirements for both the life and health insurance industries.

I am appointed; meaning that within the scope of those industries, companies have investigated me and have contracted with me to represent them. MOST importantly, these are companies that I chose. These are the companies I believe are the best in the industry at what they do. I stand always committed to these companies and each year, I go through a series of certifications and recertifications for nearly all of them.

Health Insurance Appointments for 2018

  • Humana
  • Anthem Blue Cross/Blue Shield
  • Mutual of Omaha
  • Cigna
  • Guarantee Trust Life (GTL)
  • Aetna
  • Gateway
  • SilverScripts
  • UnitedHealthOne
  • Golden Rule
  • Delta Dental
  • Bright Idea!

Life Insurance Appointments for 2018

  • Humana
  • Anthem Blue Cross / Blue Shield
  • Ameritas
  • Protective Life
  • Security Life Insurance
  • Transamerica
  • Phoenix
  • PHL Variable Insurance Company
  • and several others in process

This means that I help people with all sorts of healthcare insurance relation’d needs, as well as, I help them plan and save for and spend their retirement dollars. I love financial planning as a whole. The people I still see from the 80’s when I was with Dean Witter Reynolds still like to tell me what a service I performed by having them invest in Phillip Morris, Occidental Petroleum, McDonald’s Corporation, zero-coupon treasury bonds, and a variety of 7% triple-tax-free bonds. Boy, those days are long gone, and those bonds have long-matured.

I did so enjoy the investing world; when it was suitable. I just don’t think the stock market is safe any longer; not for people my age and above. It’s just too manipulated against the small time investor. I think I prefer to stick with a little more conservative investments.

And so, this is where I am now. I returned to this business some six years ago as mentioned in part 1… because I could see that with the “baby boomers” coming of age, they were going to need a lot of help. The boomers need solid advisers to help them with healthcare and retirement planning in this uncertain age.

So, that’s what I do. I do it for myself and I do it for all the people around me since they are all my age and above. I help people “figure it out”. I help them save. I help them shelter. I help them avoid unnecessary taxation. I help them avoid unnecessary healthcare expense. I do what I can. A lot of times it is just too late for me to do much.

When I meet with a “turning 65” year old and they look worried about a $32/month Medicare plan because they are not sure if they can afford the premiums, well I know I have someone that is going to have even a much harder time down the road if they should become sick, and have $1,000’s of dollars in healthcare expenses that the plans do not pay for. Oh yah. That happens every day.

Or when I get the call from a client asking me what the cost is for $10,000 in “final expense” insurance. Well, this is someone that has struggled probably all their life. They were not even able to plan for their last expenses until the very end, when it was the most financially difficult? I see it all the time.

It’s very hard on me. Here is a rule of thumb for you to consider; and I pray that you listen to me on this, and learn from the lesson.

The harder the sell by your insurance adviser; probably the better the product is; whatever it is… for you.

For instance, let me tell you some of the products that are the hardest to convince people they need.

Critical Care Insurance – This is very specialized coverage that ALL of us need to protect us in the event we come down with one of the big three (Do you know them? Heart attack. Stroke. Cancer.) Did you know that these three combined are the cause of death for about 70% of seniors that do not die from some type of accident?

So, what did I just tell you? Basically, IF you live to be 65 years old, that more than likely (70%) when you die it might be because of heart attack, stroke, or some form of cancer.

The big 3.

There are these truly wonderful policies that will pay you money if you are ever diagnosed with one of these three. You do not have to die from it… just be diagnosed. And yet, people do not want to spend the money for these policies. It’s just not relevant. Well, not until they feel a breast lump; or a man finds blood in his urine. Then they start wondering and asking questions. Too late. You have to get insurance before you get the illness! People always seem to forget this fact.

Lord help me, if you have one of these in your family tree somewhere, you need one of these policies. Watch a short video by Dr. Marius Barnard, the South African physician that invented the industry more than twenty years ago. It’s excellent.

Imagine finding out that you have Cancer; calling your insurer and they send you a check for $50,000 to put in the bank, pay yourself, while you fight the illness. How glorious.

Imagine having a heart attack and they actually SAVE you. It happens all the time these days; largely due to the fact we are so connected real time through cell phones and the internet, and there are such really good drugs that the paramedics and administer now… raise your heart rate, slow your heart rate. They can nearly make you even do flips if they want. So, good news… they can save your life. And after the hospital sends you a bill for $50,000 for doing so (even if you have decent insurance), you can throw that on the pile you have received from everyone else, because you cannot go back to work right away. Right?

See? That’s the problem. Even if you have insurance, you still have healthcare expenses at the same time that, guess what, you CANNOT WORK. So, you can’t kill it at the J-O-B cause “it” nearly killed you, and at the same time, the bills are mounting.

Is it any wonder that medical expenses are the largest contributor to bankruptcy cases these days?

Don’t even get me started on the need for quality Long-Term Care coverage. Very, very expensive. I just priced a policy for my girl friend and myself. Are are both around 55 years old and for a really good policy, the cost is around $650 a month for the two of us. That’s a lot of money.


Part 1 – A Little More Than a Biography 

Part 3 – Here Are My Plans for the Future
Part 1 – A Little More Than a Biography

by Michael Todd Oldfield, April 9, 2018

MY EARLY YEARS IN FINANCIAL SERVICES

It occurs to me that some people would like to know more about me than a canned “bio”. And being that I love to write, I thought I would take some time to tell you about my ongoing career in financial services and a little bit about what I do for my clients.

Today I am 55 years old. Almost 56 actually. I look in the mirror and wonder; whose the old fart? It’s funny. They say that 65 is the new 50… and 50 is the new 40. I don’t know. I am happy to be 55 although sometimes I feel 65. I just want to know who the old fart is. Is that wrong?

Oh. Born and raised in Lexington, Kentucky. I proudly serve families and individuals all over the beautiful state of Kentucky.

I began my career in financial services in roughly 1981; more than 37 years ago. I was a licensed, life agent only at that point, representing a company called Security Financial, which I think was a subsidiary of PennCorp Financial. Security Financial had a very odd product called Driver’s Security; a life insurance policy that paid off only in the event the policy holder died in a car, bus, or truck accident. If desired, a policy owner could add additional riders that would cause the policy to pay off in the event they were killed in a bus accident or on a tractor. The policies only paid off in five, ten, or fifteen thousand dollar amounts. The most you could sign up for was a measly fifteen thousand dollars. Obviously the policies were very affordable. They only cost $59-$159 per year in premium depending on whether you wanted five or fifteen thousand in coverage. There was no health underwriting. Very simple to sign people up for. They definitely fit a niche market in Kentucky; being that we have a LOT of poor farmers on tractors here.

It was a fun job. I was only 18 years. EIGHTEEN! Within three months I was a manager building my own group of agents. However, being that I was so young and immature, I did not remain in the industry long however. I was only eighteen; again. I just was not ready to build a sales career as a financial adviser at that young age. I am not sure I even made it a year. But, I knew I liked the work. I liked helping people make financial decisions. I am honest and I think that comes through when I talk to people.

In October, 1987 I re-entered the industry in a big way. I was hired by Dean Witter Reynolds (now they are Morgan Stanley) to enter their broker training program. Now this was a big job. It was estimated that Dean Witter invested more than $40,000 in each trainee to teach them the business. Looking back I still cannot imagine that they chose me. Although, I definitely showed talent for the work.

My first day was October 26, 1987 which was settlement day for “Black Monday”; the biggest one day stock market crash in history. Now, while you might think this was a terrible time to begin a career with such a prestigious organization. But, it turned out to be just the opposite. It was a perfect time to begin this career. The financial world was in shambles. Investors were lost, bewildered. Their fortunes were 1/2 gone almost; and their current broker or brokers were not returning their calls. They were scared and alone.

Their current investment advisers were hiding from all their calls. Wouldn’t you if you had been the adviser? Imagine for a moment, unexpectedly, in the matter of a few hours, all your clients; people that trusted you had seen a bunch of their net-worth evaporate. there was nothing you could do. If you had 1,000 clients you just could not make time to speak to them all in time. I am kind of glad that I began a week after that crash.

For a young guy with a lot of ambition, it was a perfect time to join the industry. Once I completed the in-depth four month training to get my securities license, including a month in New York City working in the World Trade Center II; All I had to do was create a list of people to call, and start calling them. I must have called 50-200 per day; easy. And signing them up as clients was not difficult. I am an honest, fun, intelligent guy trained by an excellent, leading company in the industry with excellent, conservative growth and fixed-income ideas. They loved me.

I offered great investment ideas and I helped a lot of people. My clients cooked dinner for me. They took me to antique auctions. Lunches. Racquetball matches. Horse races. I was having a blast. I learned so much. I lived the life fully and read everything I could on economics and investing. I could show seniors how to create tax-free retirement incomes above 7%. In fact, during the late-80s and early-90s it was not uncommon for seniors to be able to live on their retirement interest entirely. Boy, those day are gone forever it seems.

I held so many licenses and certifications. I was series 6, 7, 63 licensed of course. Those are the most common securities licenses. I also had my Series 23 and 24; and my life license because I loved writing Annuities. I was licensed as a commodities principal, a registered options principle, and later on licensed to be a manager of others in the industry. I was really credentialed well.

On the anniversary of my first three years in the business, out of the one hundred and six agents that begin in my initial training class in 1987, I was ranked 3rd; quite a nice recognition. I was really good at the work. I found excellent ways for my clients to make money; safely. This was very important to me. Most my clients were seniors; many were very old. They really relied on me to help them find safe vessels for their dollars. I had to help them earn the most money possible with the least amount of risk. I took my fiduciary responsibility very serious. I still do; even more so these days.

CURRENTLY…

Today, I do the same thing, but from a different angle. I am a licensed health and life agent in the state of Kentucky; and an independent broker. I don’t advise people on securities any more; only various insurance products. i have thought from time to time about re-licensing myself as a securities broker again, but the reality is; I am at a different place in my life. I am now an old guy; servicing seniors. I understand their concerns as they were my own. I am very, very conservative and risk-adverse personally.

I have no confidence in the stock markets. I am not confident in our ability to make money safely in those markets. I just think the whole thing is so manipulated these days. It’s just not real I feel. There is no way that I could begin to place my own money in the markets; and risk 1/2 of it in the process; which is always the case I think. I cannot do risk for myself. I just do not have the time. I have about ten peak earning years left in me. Then it will be time to coast on into the finish line. This is my last sprint. My clients are mostly fifty to eighty years old. They cannot take risks that I cannot take. Many are much older than I am. The older we get, the less risk we can afford to take in life. We cannot shoot for big gains which require big risk. We need to know for sure what we re going to have when we retire… or else we will end up greeting better prepared seniors who are shopping our local Wal-marts. Right?

We have to be prepared. We have to plan our finances wisely so as to have the most stable retirement income possible.

And it’s getting harder and harder; what with healthcare costs shooting up, care costs being outrageous, interest rates being next to nothing; and Medicare and Social Security being one step from the chopping block. Can any of us even believe in the viability of Social Security any longer? I have said for my entire life that when it was my turn; it would be gone.

THE TAKE AWAY

At this point, I just wanted to share with you a little bit about my background and where I am today. All told, at this writing, I guess I have really about thirteen years experience in our business and have tackled it from every aspect. I love the industry. I love helping the people. My own age and personal investment strategies have been largely tied to my age at the time I was in the business. When I was younger, I did more aggressive investing tied to growing piles of money with the highest returns; sometimes taking the highest risks. But it always seemed to work out.

These days, I advise people in the most conservative manner and select the most conservative, safe investment options to represent. My goal is nearly always preservation of capital, with the highest guaranteed returns and the most flexibility for my clients.

As we age, we have to have a more flexible investment strategy. We just don’t know what our financial needs are going to be from year to year, or month to month even.

  • Will we need hospital care?
  • Will we need long-term care?
  • Will we outlive our savings?
  • Will we have an “income gap”?
  • Will we need more or less income? What will we pay in taxes?
  • What would happen to our income if we lost our partner?
  • What would happen if our partner lost us?
  • What will we leave for our kids?

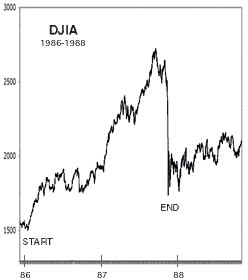
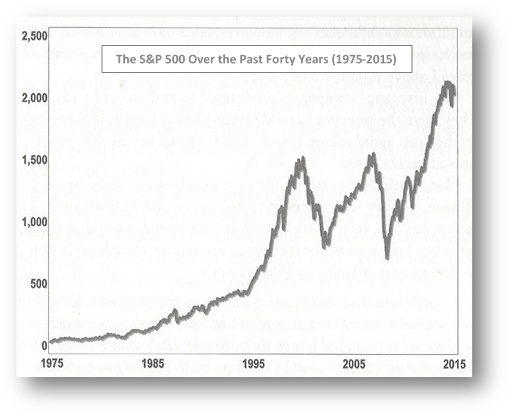
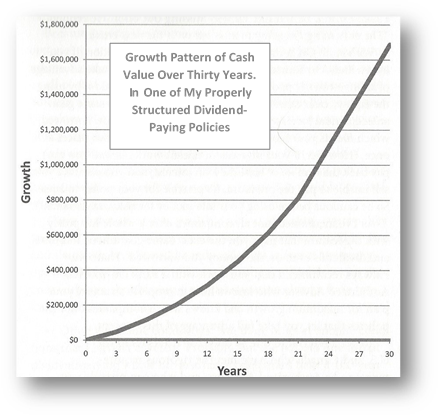
These are all questions we have to not not only know the answer to; but we need to know how to plan for these eventualities. I guess the following pictures outline what I do these days.

Sleepless Nights for 40 Years? “Bank on Yourself” Policy owned by Pamela Yellen

I help people find guaranteed returns, guaranteed income, with the least amount of risk and tax liability possible. In the next installment, we will talk about this focus and how I might be able to improve your sleeping habits.I don’t know. Which chart would allow you to sleep better?

Want to know more? Then read on and we can talk about the kinds of things I do for people now, and why I choose to do them; and my plans for the future.

PART 2 – Here’s What I focus on these days and why…

PART 3 – Here are my plans for the future; ok, let’s say it…. for the rest of my life.


I Help People Get Completely Out of Debt and Save More for Retirement

I have 100 tough questions to ask you. Just look at the list below. How many of these questions can you answer? This is what I do. I help people make plans to pay off debt, save for retirement, and guarantee some of their later years a little better than they can do on their own. Let’s face it. Nothing is for certain these days. BUT, you really do have to plan at the very least. There is so much uncertainty in the world.

As a Cool Family Banker, these are some of the hardest topics to discuss with people and probably some of the most important.

  • What’s your situation currently? Are you living within your means?
  • Are you adding debt each month?
  • Are you doing well, planning for later in life? Or are you not doing so well?
  • How do you feel about your retirement income? Are you 100% sure you are going to have a great retirement or do you have some doubt?
  • How much do you have saved for retirement? What % is that of how much you will need when you do go to retire?
  • Do you even know how much you will need saved when it comes time to retire?
  • How much income will you current amount of savings generate for you?
  • How much retirement income will you need when you do go to retire as compared to that?
  • How much equity do you have in your life?
  • How much do you save now? How often?
  • Do you save at all?
  • What % of your income are you saving?
  • Are you saving or investing?
  • Do you know the difference between saving and investing?
  • Do you know what you are earning on your savings or investments or both?
  • How much of your growth is guaranteed?
  • How much of your retirement income is guaranteed?
  • Are you paying off debt?
  • How much debt do you have?
  • How much interest are you paying per year?
  • Do you have a plan on how to pay off debt?
  • Do you know what your tax rate will be during retirement?
  • Do you know what income you will need monthly during retirement?
  • Do you know much much your current savings will generate during retirement?
  • Do you know where interest rates will be during your retirement?
  • Do you know where the stock market will be during retirement?
  • How much of your savings can you afford to lose?
  • How much of your savings could your children potentially need in an emergency?
  • Will you be able to leave anything behind to your children? To your charity?

What If’s. Don’t be scared. It will Be Ok.


Whats your plan should your tax rates go up between now and retirement or during retirement (even worse)? It’s a distinct possibility. Our income tax rates are low now compared to past years… and government debt is through the roof. The money to pay that off has to come from somewhere to pay that off. More than likely it is going to come from us… their ONLY bank.

What’s your plan should you or your loved one become sick? Serious illness costs a LOT to treat. Care costs a fortune. Do you have $100K or $200K or more sitting around to pay for care, should you or your spouse become ill and need to live our their years in a facility. 

What’s your plan should you lose your ability to earn between now and when you begin your retirement? Okay. So even if you know where you are today, and where you need to get to and have a solid plan on how to get there, what would happen if you suddenly lost your ability to finish out your plan? What if you could not earn any more, effective today?

What’s your plan should the stock market’s crash between now and when you retire? We have seen this over and over again. Sometimes the market’s do not behave real well, right when we need for them to.

Come see me. Let’s make some plans together.

Getting Out of Debt & Saving for Retirement

1 … 4 5 6 7 8 … 17